

Want to Subscribe?
Read Corporate India and add to your Business Intelligence

 Unlock Unlimited Access
Published: August 31, 2026
Updated: August 31, 2026
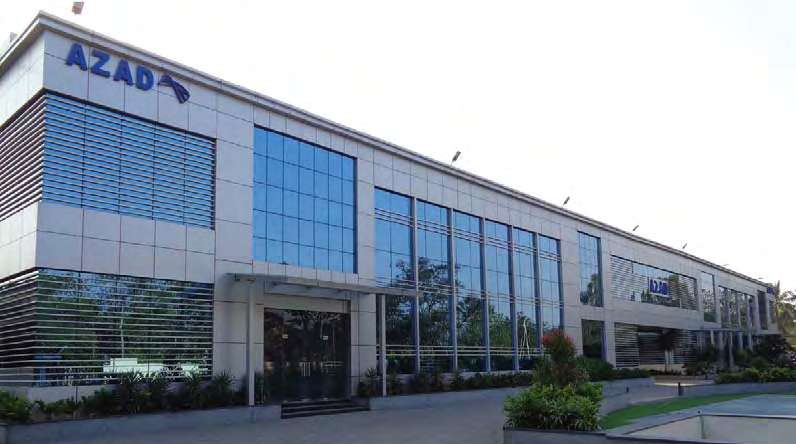
This fortnight, our Fortune Scrip focus is on a company which is not only a multi-bagger but one with high potential for sustainable growth, especially in global markets which contribute 92% to its revenues. Pertinently, the addressable market for the company’s products, which was Rs 1,500 billion in CY 2023, is expected to reach Rs 3,430 billion by CY 2029, led by the aerospace and defence sector. The company aims to corner a significant 1.5% of this market.
Hyderabad-headquartered Azad Engineering is engaged in the manufacture of high-precision mission-critical metal components and parts for the global energy, aerospace, defence and oil & gas industries. It serves as a tier 1 supplier to major OEMs worldwide. Today, it is an established supplier to global OEMs like Honeywell, Baker Hughes, Eaton Aerospace, Rolls-Royce, Siemens Energy, GE Vernova and Mitsubishi Heavy Industries, across sectors like aerospace, defence, energy and oil & gas, which have high entry barriers and strict quality control standards.
Azad is well positioned to retain its competitive lead. As on January 1, 2026, the company had in place 45+ qualified parts. It generates 92% of its revenues from international clients while the balance 8% comes from the domestic market.
The company’s financial performance is remarkable. During the last six years, sales turnover has shot up almost five times from Rs 123 crore in fiscal 2021 to Rs 603 crore in fiscal 2026, with operating profit spurting over 8 times from Rs 28 crore to Rs 225 crore and net profit registering a high jump from Rs 12 crore to Rs 134 crore. Revenues at the end of March 2026 stood at Rs 1,516 crore – over 116 times its equity capital of Rs 13 crore. But we have not picked Azad as the Fortune Scrip for this fortnight on the strength of its past performance. We are highly confident that future prospects for the company are all the more promising. Consider:
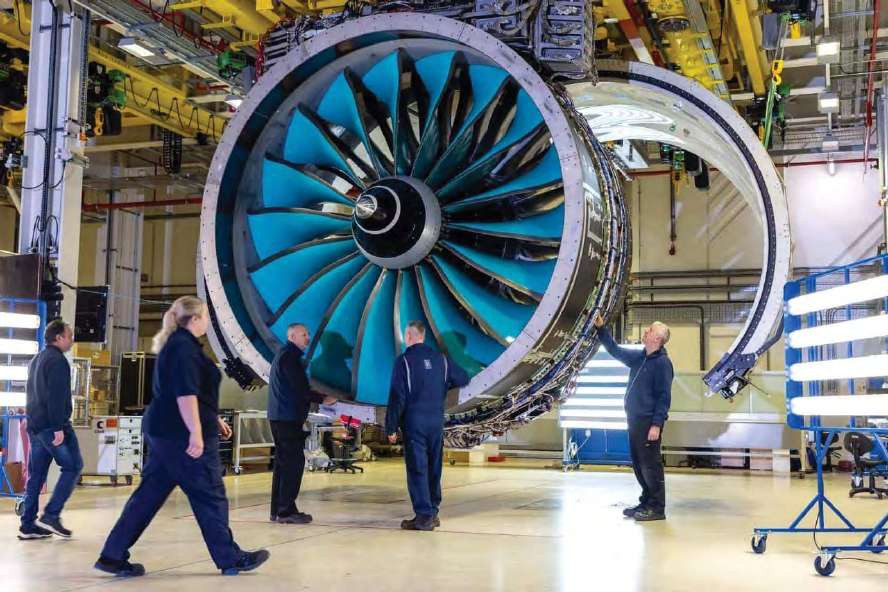
The company will be able to sustain the pace of growth going ahead as the government’s policy favouring the speedy growth of the aerospace and defence sectors, especially initiatives like ‘Make in India’ and ‘Atmanirbhar Bharat’, will help boost its top- as well as bottomline. Again, global geopolitical tensions are pushing up demand for the company’s products, leading to its embarking on a capacity expansion programme.
With orders pouring from domestic as well as global markets, the company is sitting on a robust order book of over Rs 65 billion, which should help treble its revenues over the next 3-4 years. Given the fact that most of its customers in the energy business are themselves enjoying record order books and that the domestic aerospace segment is looking up, Azad is bound to see extensive revenue growth over the next decade – limited only by the company’s response in ramping up facilities and skilled manpower.
Azad has showcased an impressive revenue CAGR of 39% over the last five years, driven by building niche capabilities in critical components. The company hopes to replicate this performance and expand capacity eight-fold in phases. At its current run rate, the order book is sufficient for nearly a decade, while order book additions are largely dependent on the timely completion of the 95,000 sq m facility in the Tuniki Bollaram area. According to the management, 3 of 7 dedicated units have been commissioned and newer plants are expected to be stabilised by fiscal 2027 and achieve maximum utilisation levels by fiscal 2028.
The management is highly confident about the rapid growth of the company going ahead. It is fully confident of achieving 25% growth beyond fiscal 2026, and has guided for EBITDA margins in the range of 33%-35% as utilisation levels improve by fiscal 2027. In the case of working capital, targets of 140-150 days are in place for the second half of FY 2026.
The company’s current share in the total addressable market (TAM) for the products for which Azad is qualified is a mere 1%. The company is an approved supplier for major players in the energy, aerospace, defence and oil & gas segments. Furthermore, its recent order wins are spread across the domains of defence, aerospace, energy and oil & gas, enhancing its presence across these verticals.
What is more, Azad is expanding capacity for further growth. It recently commissioned two new manufacturing facilities, particularly for GE Vernova and Mitsubishi, with a total area of 14,800 sq m at Hyderabad. With these two new facilities, the company now operates six state-of-the-art manufacturing facilities in Hyderabad which are equipped to produce high-precision forged and machined parts in a total manufacturing area of 34,800 sq m. Additionally it plans to establish multiple sub-facilities at Hyderabad in two phases, dedicated to specific customers.
Overall, the company aims to transition from being a component supplier to undertaking full engine assemblies through strengthening capabilities across the value chain and expanding growth opportunities. With these opportunities and strategies in place, the management plans to boost its wallet share from the current level of 1%-1.5% to 2%-2.5% in the medium term, with a long-term goal of increasing it to 10%.
The company’s shares are ruling distinctly firm at around Rs 2,840. Knowledgeable research analysts expect the price to move up to Rs 3,300 within a year.
– Savyasachi
PERFORMANCE INDICATORS (Rs. in crore)
| Metrics | Mar 21 | Mar 22 | Mar 23 | Mar 24 | Mar 25 | Mar 26 |
|---|---|---|---|---|---|---|
| Sales | 123 | 194 | 252 | 341 | 457 | 603 |
| Expenses | 95 | 132 | 179 | 224 | 296 | 378 |
| Operating Profit | 28 | 62 | 72 | 117 | 161 | 225 |
| OPM % | 23% | 32% | 29% | 34% | 35% | 37% |
| Other Income | 2 | 5 | 10 | 32 | 11 | 46 |
| Interest | 5 | 14 | 52 | 47 | 18 | 31 |
| Depreciation | 9 | 13 | 17 | 21 | 29 | 53 |
| Profit Before Tax | 16 | 40 | 13 | 81 | 124 | 187 |
| Tax % | 29% | 27% | 36% | 27% | 30% | 29% |
| Net Profit | 12 | 29 | 8 | 59 | 87 | 134 |
| EPS in Rs | 76.00 | 194.69 | 51.28 | 9.91 | 13.52 | 20.58 |
| Dividend Payout % | 0% | 0% | 0% | 0% | 0% | 0% |
August 31, 2026 - Second Issue
Industry Review


VOL XVII - 12
August 16-31, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update