

Want to Subscribe?
Read Corporate India and add to your Business Intelligence

 Unlock Unlimited Access
Published: August 31, 2026
Updated: August 31, 2026
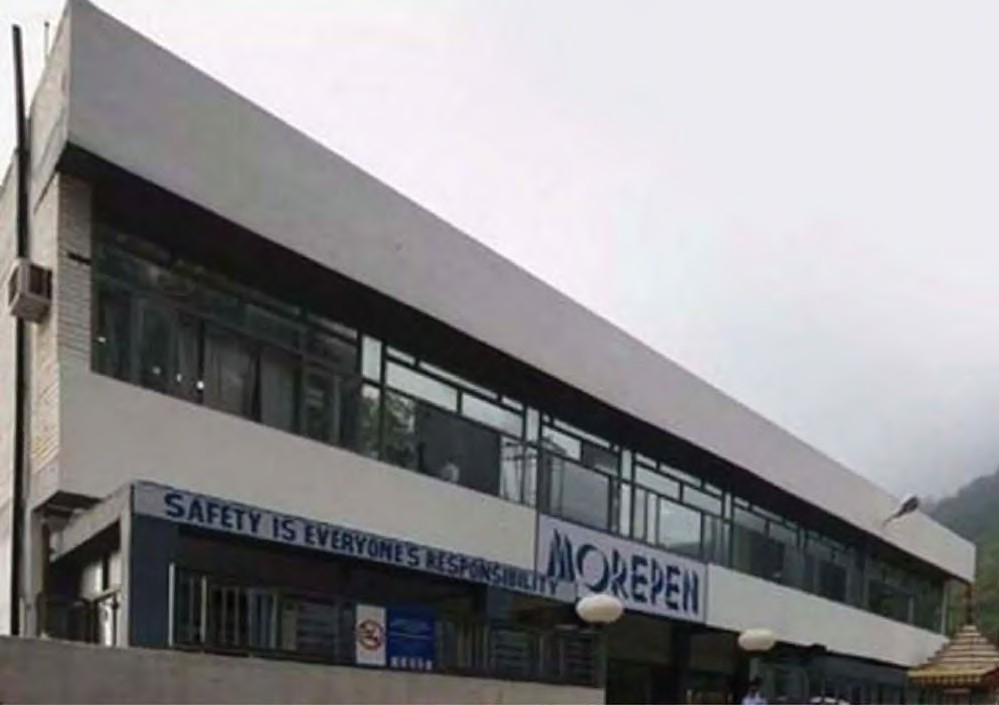
Morepen Laboratories Limited (MLL) announced its financial results for the quarter ended June 30, 2026, reporting its highest-ever quarterly revenue and highest-ever quarterly earnings, supported by better operating leverage, improved performance on the API front, strong export growth and full-scale commercialization of CDMO (Contract, Development and Manufacturing Organisation).
MLL is a vertically integrated pharmaceutical and healthcare company with over four decades of API manufacturing experience, globally approved facilities and exports across more than 90 countries. The company has established leadership positions across key APIs, supported by regulated market-compliant manufacturing infrastructure and a strong global quality track record.
MLL is progressively expanding from a traditional API business into an innovation-led manufacturing platform focused on long-duration supply contracts, CDMO partnerships, process scale-up, regulated market customer programmes and global pharmaceutical partnerships. The company is also developing its Medical Devices business as a scalable chronic-care healthcare platform across blood glucose monitoring, blood pressure monitoring, recurring consumables, CGM opportunities and connected health.
The first quarter marked a major strategic milestone as Morepen’s previously announced Rs 825-crore CDMO mandate entered a full-scale commercialization phase, with Rs 58 crore worth of commercial CDMO dispatches already completed during the quarter. This marks the commercial validation of the company’s Morepen 2.0 strategy, focused on moving from traditional commodity APIs toward innovation-led manufacturing, long-duration CDMO partnerships, recurring customer programmes and a scalable operating platform.
Commenting on the performance, Sushil Suri, Chairman & Managing Director, said, “Q1 FY27 marks an important validation of Morepen’s transformation journey. The company has delivered its highest-ever quarterly revenue, strong profitability improvement and meaningful operating leverage. More importantly, our Rs 825-crore CDMO mandate has now entered full-scale commercial execution, reinforcing our shift from a transaction-led API business to a more focused, manufacturing-led platform built around long-duration global partnerships.”
He added, “With API profitability recovering, exports growing strongly and medical devices continuing to scale as a second growth engine, Morepen is entering the next phase with greater confidence. Our focus remains on disciplined execution, capacity expansion, customer diversification and building deeper scientific and compliance capabilities to create a stronger, more predictable and globally relevant Morepen.”
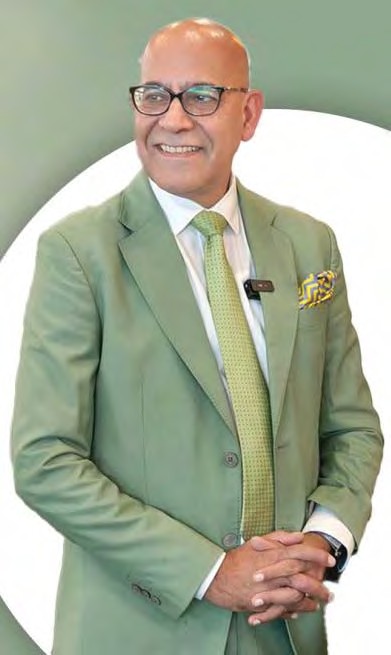
Sushil Suri, Chairman & Managing Director
The company’s API business recorded 31% growth, supported by a healthy recovery in the base business, an improved product mix, customer prioritisation and better operating discipline. API exports grew 42%, reflecting stronger traction in global markets. The company believes that a stronger API base will support the transition toward a higher-quality CDMO platform.
Q1FY27 HIGHLIGHTS
| Revenue | Rs 575.31 cr, up 34% YoY |
| EBITDA | Rs 87.72 cr, up 207% YoY |
| EBITDA margin | 15.25%, improved from 6.65% in Q1 FY26 |
| PAT | Rs 56.35 cr, up 394% YoY |
| Export revenue | Up 111% YoY |
| API growth | 31%; API exports up 42% |
| Medical devices growth | 19% |
| CDMO order | Rs 825 cr CDMO mandate enters full-scale commercialization phase |
| CDMO dispatches | Rs 58 cr commercial supply already completed in Q1 FY27 |
| Regulatory | Fourth consecutive USFDA inspections with Nil Form 483 observations |
The company’s regulatory and quality track record continues to support its global manufacturing ambitions. Morepen has completed four consecutive USFDA inspections with ‘Nil Form 483’ observations, strengthening its credibility with global pharmaceutical customers and supporting long-term CDMO partnerships. To support larger global CDMO opportunities, it is expanding its manufacturing capacity in phases. The capacity roadmap envisages expansion upto 1,200 KL by FY30.
Morepen is also building the next phase of its CDMO-led growth around four strategic pillars: capacity augmentation, global partnerships, capability scale-up and global compliance. The company’s technology road map includes deeper capabilities in small molecules, process chemistry, complex chemistry, advanced intermediates, process intensification, high-potency manufacturing, speciality APIs, difficult-to-make molecules and, over time, peptides, oligos and new modalities.
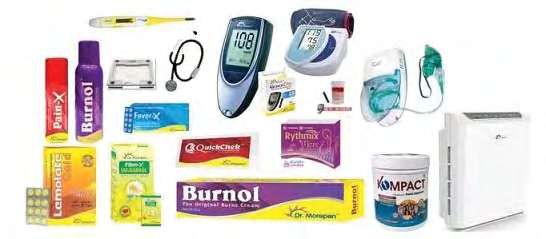
The Medical Devices business continued to provide a second scalable growth engine, recording 19% growth during the quarter. The platform is focused on chronic-care categories, including blood glucose meters, blood pressure monitors, consumables and future CGM/premium device opportunities. The business has a reported installed base of 20 million blood glucose meters and annual strip scale of 500 million strips, supporting recurring consumables revenue. Alongside the pharma transition, the company’s medical devices business continued to scale strongly, with FY26 revenue grown 21% to Rs 598 crore and an installed base of nearly 17 million repeat users.
Looking ahead, Morepen’s near-term priorities include commercial CDMO supplies, API profitability recovery and capacity utilisation. Over the medium term, the company will focus on capacity augmentation, new customer opportunities and operating leverage. In the long term, the company aims to build an innovation-led manufacturing platform anchored in global partnerships and sustainable value creation.
While commenting on the expansion of API capacity after the announcement of the Q4 annual financial results for March 2026, Sanjay Suri, Executive Director and CEO-API, had said, “We are expanding manufacturing capacity from 500 KL to 800 KL with a longer-term road map toward 1,000 KL. Increasing scale, improved product mix and long-duration supply programmes are expected to support stronger margins and earnings visibility over the medium term.”
He added, “The company has also completed a pivotal bioequivalence study for resmetirom 100 mg, an oral thyroid hormone receptor used in the treatment of moderate to advanced liver fibrosis associated with MASH. The study covers major regulated markets outside the US and represents an important step in strengthening Morepen’s globally relevant speciality pipeline.”
On 27 May 2026, the company announced its annual results when the market price of its share was Rs 42.22. Subsequently, the share has now shot up by over 109% to Rs 88.42 in less than three months, with a yearly high-low of Rs 92.50 and Rs 33 and market capitalisation of Rs 4,845 crore.
The business prospects and the company’s future road map are bright and promising. However, the equity capital of Rs 109.58 crore looks a little on the higher side. As the stock price has gone up sharply, our advice is to accumulate gradually for having the advantage of a lower acquisition cost, keeping at least a one-year investment horizon.
CONSOLIDATED RESULTS (Y.E. March: Rs. in crore)
| Particulars | Q1 FY27 (30.6.26) | FY 26 | FY 25 |
|---|---|---|---|
| Income from Operations | 570.13 | 1805.69 | 1811.58 |
| Other Income | 5.18 | 21.31 | 18.36 |
| Total Income | 575.31 | 1827.00 | 1829.94 |
| EBITDA | 87.72 | 146.93 | 192.43 |
| EBITDA Margin | 15.39% | 8.14% | 10.62% |
| Finance Cost | 4.84 | 16.41 | 8.34 |
| Depreciation | 8.35 | 36.43 | 28.98 |
| Profit Before Tax & Exceptional Items | 74.53 | 94.09 | 155.11 |
| Exceptional Items | – | 25.83 | – |
| Profit Before Tax | 74.53 | 119.92 | 155.11 |
| Tax Expense | 18.18 | 24.27 | 37.09 |
| Profit After Tax | 56.35 | 95.65 | 118.02 |
| Equity Capital (FV Rs. 2) | 109.58 | 109.58 | 109.58 |
| EPS (in Rs.) | 1.03 | 1.73 | 2.20 |
| Dividend | – | 10% | 10% |
| Book Value (Rs.) | – | 22.75 | 21.10 |
| Long-Term Borrowing | – | 133.60 | 25.76 |
| Short-Term Borrowing | – | 61.09 | 53.63 |
| Capital Work-in-Progress | – | 21.55 | 28.34 |
| Bank Balances | – | 68.83 | 49.36 |
| Promoter Group Holding | 35.65% | – | – |
August 31, 2026 - Second Issue
Industry Review


VOL XVII - 12
August 16-31, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update