

Want to Subscribe?
Read Corporate India and add to your Business Intelligence

 Unlock Unlimited Access
Published: August 31, 2026
Updated: August 31, 2026
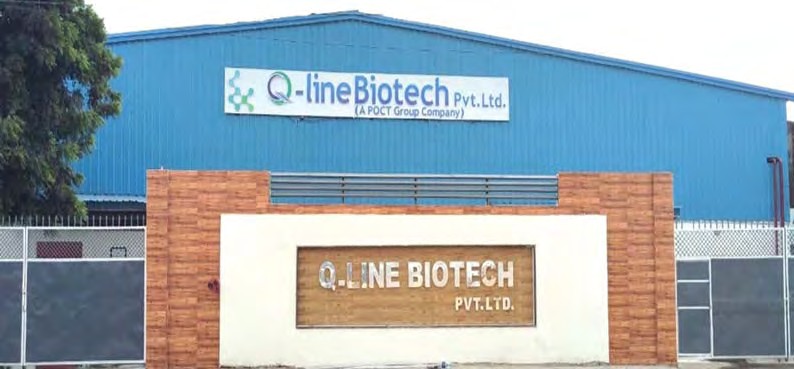
Based at Lucknow, Q-Line Biotech, recently listed on the NSE Emerge platform, is engaged in the development, manufacturing and marketing of diagnostic reagents, kits, point-of-care (POC) devices, consumables and in-vitro diagnostic (IVD) equipment.
The company has four state-of-the-art manufacturing plants. Lucknow houses its three manufacturing facilities, including the new unit commissioned in February 2026 (known as the fourth unit), significantly adding to overall capacity. The new facility will enable the company to cater to growing demand for clinical chemistry reagents, glucometers and strips. Another manufacturing unit in Bawana Industrial Area, Delhi is focusing on the indigenous manufacturing of IVD reagents.
Once unit No.4 stabilises, the company plans to shift the Delhi unit production to the new unit. There is also an unconfirmed report that the company has proposed setting up a manufacturing facility for IVD devices and reagents in the Medical Device Park of YEIDA (Yamuna Expressway Industrial Development Authority), planned to be established in 10,000 square metres.
In terms of production capacities, up to 2026 the company had an annual installed capacity of approximately 1.4 million testing kits across haematology, clinical chemistry and rapid/elisa segments. Likewise, it could manufacture and supply around 1,200 selected testing machines per annum.
The company, promoted by the Garg family led by Saurabh Garg, Chairman and Managing Director, came out with an SME-IPO to raise Rs 214.46 crore comprising 62,53,200 shares issued at Rs 343 per share with a Rs 10 face value, meant to repay debt of Rs 90 crore, with Rs 93.50 crore towards meeting working capital requirements. The issue was oversubscribed over 102 times and the stock debuted at Rs 431 on May 29, 2026.
Prior to filing the DRHP in September 2025, the promoters issued liberal bonus shares to themselves in the ratio of 9:1 (nine bonus shares for every existing share held by them). As a result, the equity capital increased manifold from Rs 1.575 crore in March 2025 to Rs 16.275 crore prior to the IPO in May 2026. Post-IPO, equity capital is Rs 23.33 crore with a book value of Rs 209.20 per share, and promoter group’s holding is at 67.51%.
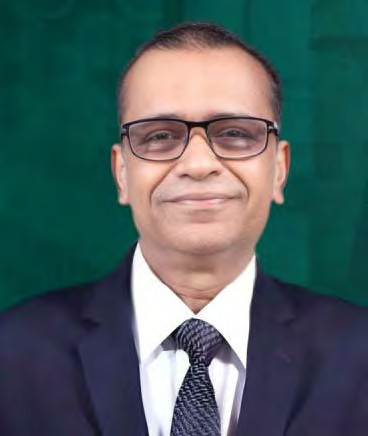
Saurabh Garg, Chairman and Managing Director
While giving an account of the company’s recently concluded IPO and outlining the business outlook, Mr Garg said, “FY 27 growth will be supported by the IPO proceeds allocated towards working capital. These funds will be utilised to expand our sales force, deepen geographic penetration and increase the installed base of instruments. A larger installed base is expected to drive recurring reagent sales, while CDMO and export operations are also expected to contribute to overall revenue growth. As we continue to invest in manufacturing, innovation and product development, we remain well positioned to capitalize on the growing demand for high-quality diagnostic solutions and create long-term value for all stakeholders.”
For FY 26, the company achieved sales of Rs 341.74 crore and PAT of Rs 56.48 crore, and recorded operating margin and RoNW of 28.60% and 21.35% respectively. Its sales grew moderately at 9.13% compared to Rs 313.14 crore in FY 25. However, EBITDA, PBT and PAT have grown quite impressively at 39%, 42% and 57% respectively. H2 of FY 26 has contributed significantly to the company’s growth momentum. If the trend continues, it could become a game-changer for a bright future.
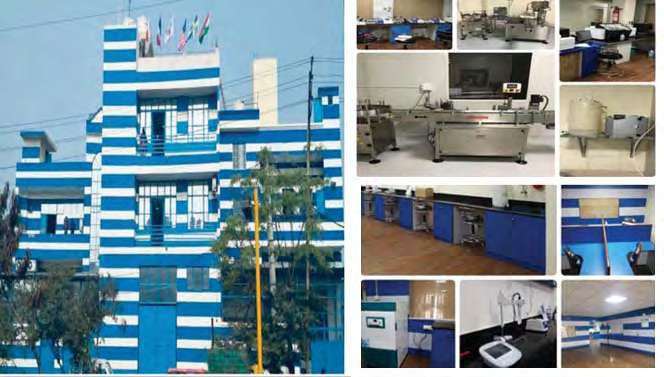
Reagents and diagnostic kits accounted for 69% of the company’s revenue during FY 26, providing a strong recurring revenue base due to their consumable nature and consistent demand from diagnostic laboratories and healthcare institutions. The sizeable improvement in EBITDA is primarily driven by nearly 70% growth in the sales of domestically manufactured reagents carrying higher margins, supported by improved operational efficiencies, favourable product mix and cost management.
Another positive development is that the company has significantly reduced its dependence on imports by localizing its manufacturing operations. It now manufactures a little over 50% of laboratory equipment in India through strategic collaborations with European technology partners, and this has started strengthening profit margins, improving supply-chain resilience and supporting the company’s overall aim of sustainable long-term growth.
It’s important to note that the contribution of traded goods was on the higher side in the past, and is now getting replaced gradually with the company’s own local manufacturing. In FY 25, of the total revenue of Rs 313 crore, traded products was 46%, which got reduced to 32.52% in FY 26. However, the company continues earning good EBITDA margins even on these traded products.
Q-Line intends to establish itself for select products in the export market, after a market survey pointed to various opportunities overseas. As part of its global growth strategy, the company has appointed a business manager in Dubai to develop, strengthen and accelerate international operations. In a promising beginning, distributor agreements have been entered into with 7-8 countries as of March 2026.
Leveraging these strategic partnerships and an expanded global distribution network, the company anticipates export revenues to grow nearly 5x in FY 27. Moreover, negotiations are also continuing to explore export opportunities of instruments manufactured here under exclusive technical collaboration to the European principals themselves. If successful, this would help deploy idle capacities in the new Unit No. 4 and would eventually contribute to incremental revenue and profits for the company.
In a reply to a query related to the company’s export business, Ajay Kumar Mohanty, CEO, said, “We have entered the export market just last year and successfully registered sales of Rs 1.18 crore during FY 26. We have registered our product and fulfilled compliance and regulatory requirements in the Middle East, Africa and Mauritius.”
Commenting on the annual performance, Mr Garg said, “FY26 has been a transformative year for Q-Line Biotech. The successful capitalisation of our largest manufacturing facility in Lucknow marks a significant milestone in our journey and substantially strengthens our manufacturing capabilities. During the year, sales of manufactured reagents increased by nearly 70%, reflecting our strategic focus on expanding in-house manufacturing, improving value addition and reducing dependence on traded products.”
He added, “We also achieved a key milestone in our instruments division, reaching an installed base of over 1,550 Selectra Pro M fully automatic biochemistry analysers, our flagship equipment product, whose manufacturing commenced in December 2023. In addition, we successfully commercialised the electrolyte analyser and are on track to launch the Micro lab 300 by Q2 FY 27, further expanding and diversifying our diagnostic instruments portfolio.”
In its revenue guidance for FY 27, the company has marked 30-35% yoy growth with a corresponding rise in the EBITDA margin. A loan repayment of Rs 90 crore from the IPO proceeds and deployment of Rs 93.50 crore in working capital will reduce the finance cost of the company, which was Rs 18.88 crore in FY 26. As of March 2026, long-term and short-term debt were at Rs 96.19 crore and Rs 129.29 crore respectively.
In the last three months after its listing, the stock hit a high of Rs 622 on August 31, 2026 and a low of Rs 487 on July 29, 2026. Currently, the market price is Rs 595.55, with market capitalisation of Rs 1,389 crore. Compared to the issue price of Rs 343, the stock has already appreciated by Rs 252.55 – by almost 74% in just a quarter.
The company’s business prospects, strategy and capabilities, supported by a technocrat promoter, look appealing for investment, but we would suggest entering at the current level cautiously and accumulating gradually because the price might face a downward correction. Being an SME, the company hasn’t announced the Q1 2026 results. Now, only the H1 2026 results will be made available. However, the fact remains that the stock has potential to reward investors over a period of time, provided things move ahead as planned.
Q-LINE BIOTECH AT A GLANCE (Rs. in crore)
| Metrics | FY25 | FY26 | Change (%) |
|---|---|---|---|
| Sales | 313.14 | 341.74 | +9.13 |
| PAT | – | 56.48 | +57 |
| Traded products share of revenue | 46.00% | 32.52% | – |
August 31, 2026 - Second Issue
Industry Review


VOL XVII - 12
August 16-31, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update