

Want to Subscribe?
Read Corporate India and add to your Business Intelligence
 Unlock Unlimited Access
Published: October 31, 2026
Updated: October 31, 2026
In operation since 1993, BSE-listed Cochin Minerals and Rutile (CMRL), a 100% export-oriented unit, was set up to produce synthetic rutile using ilmenite as the main raw material, with equity participation of 13.41% from Kerala State Industrial Development Corporation (KSIDC) and Dr S N Sasidharan Kartha’s family holding 37.96% of the total promoter group holding of 51.37%.
Synthetic rutile produced by the company is used as titanium feedstock for the production of titanium sponge and titanium metal. Since titanium metal has excellent properties like a high strength-to-weight ratio, corrosion resistance, ability to withstand high temperatures and inert properties, it is used in a variety of applications ranging from aerospace, chemical, metallurgical, electrical and electronic hardware to nuclear and biomedical.
Hi-tech titanium alloys are used in aeroplanes, rockets, satellites, automobiles, heat exchangers, mobile phones, various other electronics products, medical and dental implants. With a lower percentage of TiO2, synthetic rutile is used for manufacturing titanium dioxide pigment used for the production of paints and coatings, speciality chemicals, plastics, paper, textile, ink, cosmetics, toothpaste, pharmaceuticals, etc. It is also used as flux component for welding electrodes and as an abrasive.
Nearly 40% global hi-tech titanium requirement is met by synthetic rutile produced by CMRL. Leading Japanese companies, MNCs based in USA, Europe, China and other geographies constitute the esteemed clientele of the company.
CMRL is a leading global and domestic producer and exporter of high-purity synthetic rutile. The other two companies in the same domain are Mumbai-based DCW Ltd, which has a large-scale commercial manufacturing facility in Sahupuram near Tuticorin in Tamil Nadu, and state-owned Kerala Minerals and Metals (KMML) based at Chavara, which houses India’s only integrated titanium dioxide facility, spanning mineral separation, synthetic rutile production and pigment production.
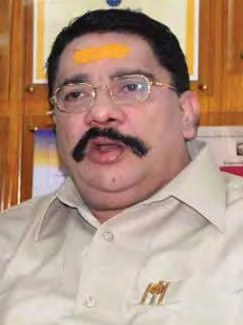
Dr S N Sasidharan Kartha
In a recent controversy involving an allegation of a bribe paid by CMRL to former Kerala Chief Minister Pinarayi Vijayan through Bangalore-based IT consultancy firm Exalogic Solutions (owned by Mr Vijayan’s daughter Veena T), the company allegedly paid between Rs 1.72 crore and Rs 2.78 crore between 2017 and 2020 for IT and marketing consultancy services that were never actually provided.
This has been alleged by the central investigating agencies, including the Enforcement Directorate (ED) and the Serious Fraud Investigation Office (SFIO). Further, the Kerala High Court has directed the state’s vigilance and Anti-Corruption Bureau to register a formal FIR against Mr Vijayan, his daughter and son-in-law.
In its disclosure to the stock exchange, the company has clarified that it has not received a copy of the FIR or an official intimation from the investigating agencies.
In another development, the company has received a GST demand of Rs 120.26 crore by the authorities, disputing the HSN classification of products for the periods 2020-21 to 2023-24, prior to the advanced ruling obtained by the company. A writ petition has been filed challenging the show-cause notice and a stay has been obtained by the company in the matter.
During Q1 of the current FY27, the company has performed exceedingly well, mainly because of an improved EBITDA margin which has gone up to 13.25% vis-à-vis 8.73% in the previous full financial year. It achieved revenue from operations of Rs 131.26 crore, EBITDA of Rs 17.39 crore, PBT of Rs 16.79 crore and PAT of Rs 12.38 crore, translating into EPS of Rs 15.81 on equity capital of Rs 7.83 crore.
By comparison, in the twelve months of FY26, revenue was Rs 294.92 crore, EBITDA Rs 25.75 crore, and PBT and PAT Rs 18.92 crore and Rs 12.51 crore respectively, and 80% dividend was paid.
The tax provision of Rs 4.41 crore in Q1 itself is a positive indicator vis-à-vis Rs 6.41 crore provided for the full year in FY26.
The company is not only net debt-free but is also cash surplus. As of March-end 2026, it had a bank balance of nearly Rs 44 crore and a non-current investment of Rs 14.54 crore vis-à-vis a short-term borrowing of Rs 6.21 crore. There is no long-term debt. Out of Rs 14.54 crore, the major amount of Rs 13.60 crore is towards share application money paid in tranches since FY 2001-02 to Kerala Rare Earths and Minerals Ltd (KREML), whose allotment is still pending.
Major Public Shareholders (30.09.2026)
| Shareholder | Qty | % |
|---|---|---|
| Anil Ananda Panicker | 1,43,772 | 1.84 |
| Investor E & P F Authority | 2,30,182 | 2.94 |
| John M T | 1,27,601 | 1.63 |
| Pushpadevi Rajora | 91,934 | 1.17 |
| Vinod Kumar Tulsian | 83,142 | 1.06 |
| Yogesh Kumar Kankaria | 96,825 | 1.24 |
| Japa Investment Advisor LLP | 87,133 | 1.11 |
| Total | 8,60,589 | 10.99 |
KREML is primarily a joint venture project incorporated in 2001 to undertake beach sand ilmenite mining and mineral separation in the coastal zones of Kerala. Though its authorised capital is Rs 20 crore, the paid-up capital is only Rs 1.42 crore. As its core mining licences were restricted, no new equity shares are scheduled for issuance to CMRL from this joint venture. Likewise, the JV’s initial plan to raise Rs 100 crore for the mining project has come to a halt.
The other share applicants in KREML from state and central entities are Kerala State Industrial Development Corporation (KSIDC) and IREL (India) Ltd, formerly known as Indian Rare Earths Ltd. Currently, the small base of issued equity predominantly represents promoter group individuals and entities linked to CMRL’s management, alongside minor nominal stakes originally intended for industrial promotion firms.
Importantly, the state government has terminated the lease deed for the proposed project in line with the amended guidelines of the Central government. The project is now reserved for the public sector on the ground that beach sands rich in monazite (the primary source of thorium) are strictly reserved for state-run undertakings due to national security and environment protection concerns.
Most recently, the Kerala High Court has stayed for four weeks, the FIRs and investigation against former Chief Minister P Vijayan and his family members in the alleged Cochin Minerals and Rutile Ltd bribery case.
Facing a permanent block on private sand mining, KREML has shifted its focus to setting up a downstream value-added mineral complex at an estimated investment of Rs 3,000 crore. As such there are no concrete updates-formal announcements are available in this regard. However, being the publicly listed company, it is equally important to know the fate of Rs 13.60 crore paid by CMRL to KREML almost over more than two decades.
The original promoter of CMRL, Dr S N Sasidharan Kartha, has taken a back seat on health grounds and Saran Kartha Sasidharan has become Managing Director of the company. In another important move, Dr Rabinarayan Patra, a freelance consultant on processing technologies, has been appointed recently as non-executive Chairman. Dr. Patra holds a PhD in Chemical Engineering from IIT, Kharagpur. He is a former Chairman & Managing Director, Indian Rare Earths Ltd. He joined Bhabha Atomic Research Centre (BARC) in 1977 and superannuated as CMD of IREL in 2015.
Undoubtedly, the dedicated rare earth corridor proposed in the Union budget primarily for the four coastal states of Odisha, Kerala, Andhra Pradesh and Tamil Nadu augurs well for CMRL, especially considering its planned Rs 3,000-crore strategic mineral value-added downstream project. Further, its current operations of synthetic rutile is well-established and running quite profitably. Hence, the business prospects and the promoter group’s capability and proven track record are favourable indicators. However, at this point of time, it is necessary for the company to come clean over the bribery allegations involving former Kerala Chief Minister P Vijayan’s daughter’s company, Exalogic Solutions. Likewise, it is also desirable and prudent for the company to resolve the GST demand of Rs 120.26 crore.
After a stellar Q1 show, the share price of CMRL had gone up to Rs 330 and has now corrected to the Rs 250 level, with a yearly high-low of Rs 330-197. The market capitalisation is Rs 196 crore and book value is at Rs 219.70 per Rs 10 face value share. The stock is worth monitoring closely and after dust settles, discerning investors can buy it, keeping at least a one-year horizon. The company also needs to implement the Rs 3,000-crore downstream value-added mineral project successfully, as it is also equally important for its sustained growth ahead.
Financial Indicator (Rs. cr)
| Q1 27 (30.06.26) | Q1 26 (30.06.25) | FY26 | FY25 | |
|---|---|---|---|---|
| Revenue from Operation | 131.26 | 76.21 | 294.92 | 319.21 |
| Other Income | 2.06 | 1.36 | 2.27 | 8.20 |
| Total Income | 133.32 | 77.57 | 297.19 | 327.41 |
| EBITDA | 17.39 | 5.43 | 25.75 | 39.07 |
| EBITDA Margin (%) | 13.25% | 7.13% | 8.73% | 12.24% |
| Finance Cost | 0.05 | 0.07 | 0.19 | 0.20 |
| Depreciation | 0.55 | 0.29 | 1.59 | 1.13 |
| Profit Before Tax (after exceptional item) | 16.79 | 5.07 | 18.92 | 37.74 |
| Tax Provision | 4.41 | 1.80 | 6.41 | 14.18 |
| Profit After Tax | 12.38 | 3.27 | 12.51 | 23.56 |
| Equity Capital (FV Rs.10) | 7.83 | 7.83 | 7.83 | 7.83 |
| E. P. S. | 15.81 | 4.17 | 15.97 | 30.09 |
| Book value (per share) | 219.70 | 211.23 | ||
| Long-Term Borrowing | – | – | ||
| Short-Term Borrowing | 6.21 | 10.78 | ||
| Bank Balances | 43.73 | 27.65 | ||
| Dividend (%) | 80 | 80 | ||
| Promoter Group Holding (%) | 51.37 | 51.17 | 51.35 | 51.17 |
October 31, 2026 - Combined Issue
Industry Review


VOL XVII - 14
October 16-31, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update