

Want to Subscribe?
Read Corporate India and add to your Business Intelligence
 Unlock Unlimited Access
Published: October 31, 2026
Updated: October 31, 2026
For this fortnight, we have selected a company that is unusual in that it does not belong to a ‘standard’ industry segment. However, it has remarkable growth potential. Listed on NSE and BSE, it is a multi-bagger stock with prospects of scaling further highs.
Gravita India, headquartered in Jaipur (Rajasthan), was promoted by first-generation entrepreneur Rajat Agrawal way back in 1992. Today, it is a prominent global player in the recycling industry, specialising in recycling of lead, aluminium, plastic and rubber. This integrated recycling company is focused on building sustainable and efficient material recovery ecosystems. During the 34 years of its existence, it has grown into a diversified, multinational recycling entity with operations across Asia, Africa and Europe.
Its state-of-the-art lead processing unit at Jaipur carries out smelting of lead ore/lead concentrate/lead battery scrap to produce primary and secondary lead metal which is transformed into pure lead, specific lead alloy, lead oxides (sub-oxide), red lead and litharge, and lead products (lead sheets, lead pipes, etc.).
PERFORMANCE INDICATORS (Rs. in crore)
| Mar ‘22 | Mar ‘23 | Mar ‘24 | Mar ‘25 | Mar ‘26 | |
|---|---|---|---|---|---|
| Sales | 1,894.18 | 2,524.39 | 2,679.07 | 3,222.77 | 3,481.37 |
| Operating profit | 78.26 | 99.43 | 199.58 | 223.09 | 312.47 |
| Interest | 27.87 | 32.21 | 31.21 | 22.19 | 9.38 |
| Gross profit | 57.68 | 126.94 | 221.58 | 248.11 | 380.48 |
| EPS (Rs) | 5.76 | 14.65 | 26.01 | 26.30 | 40.25 |
| Research and development expenses | |||||
| Depreciation | 8.93 | 10.69 | 13.36 | 15.19 | 17.90 |
| Taxation | 9.00 | 15.10 | 28.60 | 38.79 | 65.56 |
| Net profit / loss | 39.75 | 101.15 | 179.62 | 194.13 | 297.02 |
| Equity capital | 13.81 | 13.81 | 13.81 | 14.76 | 14.76 |
| Reserves | 194.08 | 294.72 | 442.69 | 1580.38 | 1832.08 |
| In rupees per share | |||||
| Book Value | 56.02 | 85.09 | 121.27 | 280.48 | 358.40 |
| EPS (Rs.) | 3.00 | 4.35 | 5.20 | 6.35 | 7.70 |
| Dividend (Rs.) | 02 | 02 | 02 | 02 | 02 |
| Face Value | |||||
| Ratio OPM (%) | 4.13 | 3.94 | 7.45 | 6.92 | 8.98 |
| GPM (%) | 3.03 | 4.91 | 8.11 | 7.59 | 10.69 |
| NPM (%) | 2.09 | 3.91 | 6.57 | 5.94 | 8.35 |
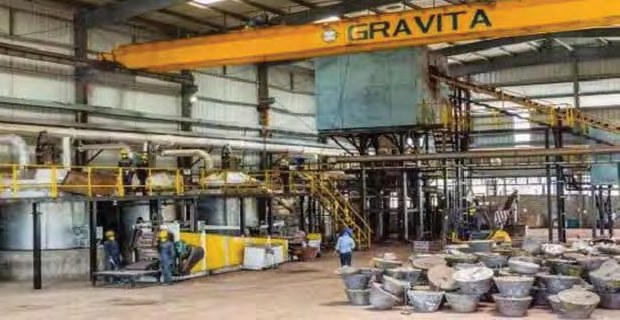
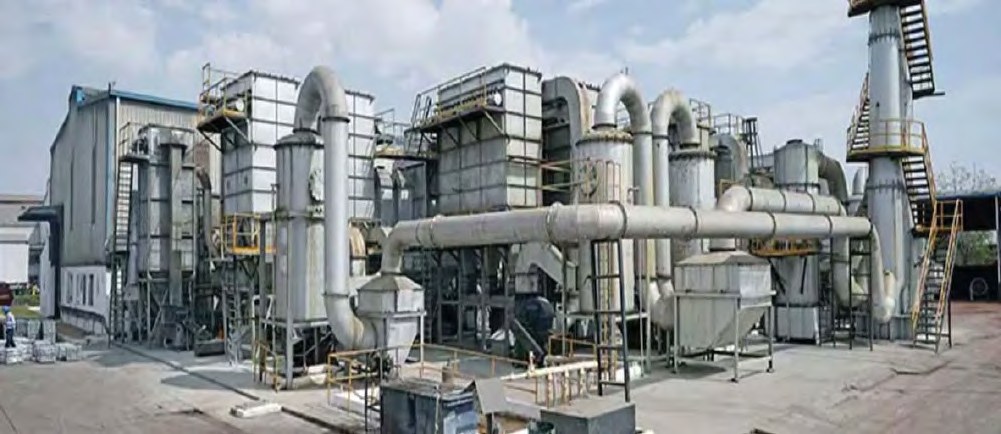
Beside Jaipur, the company operates advanced recycling and manufacturing facilities at Kathua (Jammu & Kashmir), Mundra (Kutch, Gujarat) and Chittoor (Andhra Pradesh), as well as units in Romania, Ghana, Mozambique, Togo, Senegal, Tanzania and Sri Lanka. The company has a strong global procurement network, and serves customers in more than 70 countries.
Gravita’s core business spans lead battery recycling, aluminium alloy manufacturing, plastic recycling and waste tyre recycling. Its product portfolio includes specialised lead alloys, plastic granules, recovered carbon black and tyre pyrolysis oil (TPO). The company has also executed 70 turnkey recycling projects globally, offering end-to-end solutions from design and engineering to commissioning.
As part of its strategic expansion, Gravita has launched a dedicated lithium-ion battery recycling plant at Mundra (Kutch, Gujarat). The company has also signed a binding agreement to acquire a majority stake in Rashtriya Metal Industries Ltd (RMIL), thus strengthening its presence in non-ferrous metals.
During the last 13 years, its sales turnover has shot up more than eight times from Rs 501 crore in fiscal 2015 to Rs 4,265 crore in fiscal 2026, with operating profit spurting almost 22 times from Rs 20 crore to Rs 439 crore and the profit at net level zooming almost 38 times from Rs 10 crore to Rs 378 crore. The company’s financial position is extremely strong, with reserves at the end of March 2026 standing at Rs 2,437 crore – over 162 times its tiny equity capital of Rs 15 crore.
But we have not picked Gravita as the Fortune Scrip on account of its past laurels. We are confident that prospects for the company going ahead will be even more promising. Consider:
According to a renowned research analyst, future prospects for Gravita India are heart-warming. The company is forecast to grow earnings and revenue by 22.8% and 28.5% per annum respectively. EPS (earnings per share) is likely to grow by 21.5% per annum. Return on equity (RoE) is forecast to be 20.2% in 3 years. (This analysis was last updated on October 14, 2026.)
Prospects for the company’s stock are excellent. In the current depressed market situation, the Gravita stock with a face value of Rs 2 is quoted in the Rs 1,475-1,480 range. Once the war drums in West Asia stop, the stock price could start moving up to Rs 2,000 and above.
– Savyasachi
October 31, 2026 - Combined Issue
Industry Review


VOL XVII - 14
October 16-31, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update