

Want to Subscribe?
Read Corporate India and add to your Business Intelligence
 Unlock Unlimited Access
Published: October 31, 2026
Updated: October 31, 2026
Sanjay Aggarwal, Chairman & CEO
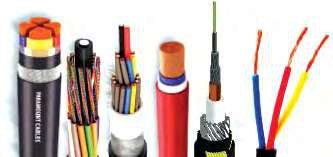
NSE-BSE listed Paramount Communications is a decades-old manufacturer of wires and cables with a diverse portfolio of high-performance cable solutions across the power, telecom, railways, renewables, defence, space, IT, construction and oil & gas sectors. Its products include power cables, optical fibre and telecom cables, railway signalling and axle counter cables, building wires, fire-survival cables, solar cables, HTLS conductors and other specialised cables. The company also undertakes EPC and turnkey projects, including HTLS and OPGW installation and submarine cable laying and repair.
Paramount operates two state-of-the-art manufacturing facilities in Dharuhera, Haryana and Khushkhera, Rajasthan. With a strong domestic presence and an expanding international footprint, it serves over 950 institutional clients and has established itself as a trusted partner across critical infrastructure and industrial applications.
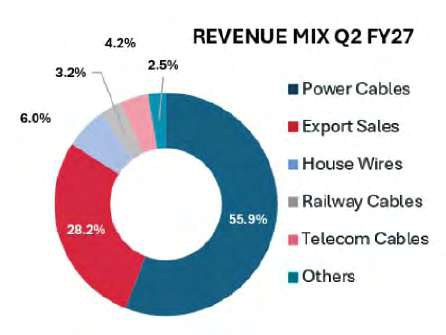
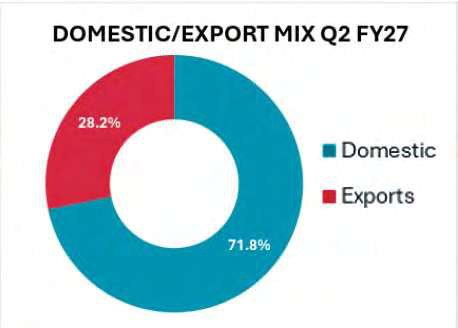
During H1FY27, revenue from operations stood at Rs 1,089.8 crore against Rs 878.5 crore in the previous period, registering 24.1% growth. EBITDA and PAT margins showed a modest rise at 7.5% (PY 6.4%) and 4% (PY 3.5%) respectively, translating into a six-month EPS of Rs 1.38 vis-à-vis Rs 1.06; i.e., 30.2% up. Export revenue contributed Rs 158.1 crore in Q2 (28.2%), whereas domestic sales of Rs 402.30 crore remained at 71.8% of total sales. Amongst the revenue mix, power cables is the largest contributor at nearly 60%.
For FY26 (12 months), on operational revenue of Rs 1,964 crore, it achieved PAT of Rs 60.24 crore, converting into EPS of Rs 1.97. Its long-term borrowing is negligible, whereas short-term borrowing went up steeply from Rs 22 crore in FY25 to Rs 114 crore.
The order book of Rs 731 crore as on Sept 30, 2026 provides a reasonably good comfort zone to near-term revenue visibility. The company’s third manufacturing facility, spread across 31 acres at Narmadapuram, Madhya Pradesh, is coming up for the manufacture of EHV cables up to 220 kV, and its partial commissioning is expected in Q1FY28. The management expects this new plant to contribute Rs 500 crore in FY28 and Rs 1,200 crore in FY29 to operational revenue.
Commenting on the results, Sanjay Aggarwal, Chairman & CEO, said, “Paramount’s performance reflects the resilience of our business model, the strength of our customer relationships, and our ability to respond decisively to changing market conditions. We remain focused on sustainable growth and financial discipline.”
Outlining the demand scenario, he said, “The structural demand outlook for the wires & cables industry remains encouraging, driven by investments in power transmission and distribution, renewable energy integration and critical infrastructure. As power generation capacity expands, strengthening the infrastructure required to transmit and distribute electricity efficiently will be equally important, creating meaningful long-term opportunities for established players with proven capabilities.”
He added, “Our priorities remain clear: strengthening our core business, restoring operating profitability, expanding our international presence prudently and enhancing our product mix. Investments in specialised manufacturing capabilities will enable us to address more technically demanding applications and participate in higher-value segments. We remain committed to disciplined capital allocation, prudent risk management and translating the industry’s long-term growth potential into sustainable performance and enduring stakeholder value.”
Currently, the stock is available at around Rs 65 with a yearly high-low of Rs 76-28, and market capitalisation of Rs 2,145 crore. The promoter group holds 45.87% and the book value per share is Rs 26.60. It might appear that the company is not getting a fair valuation compared to its peers in the listed space. However, it is mainly because of poor EBITDA and PAT margins and premature higher equity capital of Rs 65.45 crore. Therefore, the stock is certainly worth putting on one’s watchlist. As such, the downward risk also looks limited. The commencement of its third plant could possibly impact rerating of the stock positively.
Financial Performance (Rs. cr)
| Particulars | Q2FY27 | Q1FY27 | H1FY27 | H1FY26 | YoY |
|---|---|---|---|---|---|
| Revenue from Operations | 560.4 | 529.4 | 1089.8 | 878.5 | 24.1% |
| Total Income | 564.2 | 532.5 | 1096.7 | 916.4 | 19.7% |
| Operating Profit (excl. OI) | 40.9 | 34.7 | 75.6 | 20.9 | 262.5% |
| Operating Margin (excl. OI) | 7.3% | 6.6% | 6.9% | 2.4% | 450bps |
| EBITDA (incl. OI) | 44.7 | 37.8 | 82.5 | 58.8 | 40.3% |
| EBITDA Margin (incl. OI) | 7.9% | 7.1% | 7.5% | 6.4% | 110bps |
| Profit After Tax | 24.2 | 19.7 | 43.9 | 32.3 | 36.2% |
| PAT Margin | 4.3% | 3.7% | 4% | 3.5% | 50 bps |
| EPS (Rs.) | 0.74 | 0.64 | 1.38 | 1.06 | 30.2% |
October 31, 2026 - Combined Issue
Industry Review


VOL XVII - 14
October 16-31, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update