

Want to Subscribe?
Read Corporate India and add to your Business Intelligence
 Unlock Unlimited Access
Published: September 30, 2026
Updated: September 30, 2026
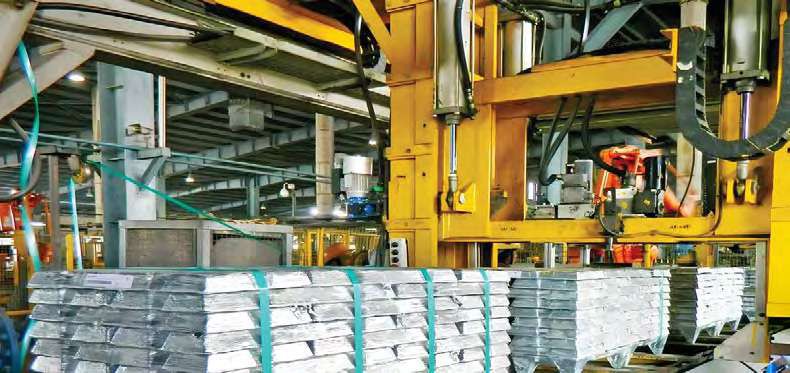
This time we have picked a unique central PSU-turned-private sector entity as the Fortune Scrip. The company, which was a public sector enterprise till the end of the 20th century, was privatised in 2002 and went into the fold of the Vedanta group headed by Anil Agarwal.
Established in 1966 as a government of India-owned PSU, HZL started producing zinc, of which there was an acute shortage, obliging India to depend on large imports for its requirements. But typical of a government PSU, the company’s productivity was very low, output moderate and profitability not worth writing home about. With a growing shortage of zinc at home and rising imports, the government sold the company (controlling equity stake) to the Vedanta group in 2002. The Vedanta group supremo, Mr Agarwal, transformed the company, leading to a remarkable improvement in operational efficiency, an upswing in production and a marked improvement in profit margins.
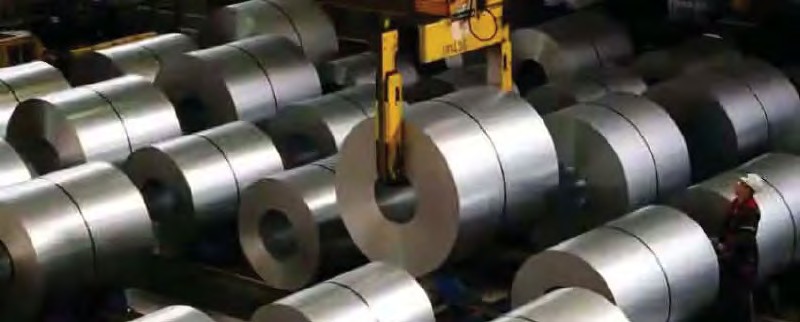
By now, HZL has emerged as the largest zinc producer in India, the second largest integrated zinc producer in the world, and the third largest global producer of silver (a by-product). Today, HZL is an undisputed industry leader in zinc in India and a noted market leader in zinc at the global level. The company is recognised for its operational excellence, financial acumen, innovative approach at every stage, technological supremacy, consumer centricity, ethical governance and remarkable ESG practices.
The Udaipur-headquartered company now runs a fully integrated mine-to-metal operation with facilities across Rajasthan and Uttarakhand. In fiscal 2026, it delivered a record mined metal output of 1,114 kt and a refined metal production of 1,048 kt, alongside silver production of 627 mt. Zinc, which accounts for 81% of the refined metal portfolio, reached 851 kt, reinforcing the company’s dominant position with an estimated 74% share of the domestic primary zinc market.
HZL has been doing exceedingly well in its financial performance. During the last 12 years, its sales turnover has almost trebled from Rs 14,788 crore in fiscal 2015 to Rs 40,658 crore in fiscal 2026, with operating profit also almost trebling from Rs 7,480 crore to Rs 21,929 crore and the profit at net level inching up from Rs 8,178 crore to Rs 13,712 crore. The company’s financial position is very strong, with reserves at the end of March 2016 standing at Rs 21,630 crore – over 21 times of its equity capital of Rs 845 crore.
But we have not picked HZL as the Fortune Scrip for this fortnight on account of its past laurels. We are confident that the company’s prospects going ahead are equally promising. Consider:
PERFORMANCE INDICATORS (Rs. in crore)
| Metrics | Mar 22 | Mar 23 | Mar 24 | Mar 25 | Mar 26 |
|---|---|---|---|---|---|
| Sales + | 29,440 | 34,098 | 28,934 | 33,969 | 40,658 |
| Expenses + | 13,214 | 16,577 | 15,253 | 16,630 | 18,729 |
| Operating Profit | 16,226 | 17,521 | 13,681 | 17,339 | 21,929 |
| OPM % | 55% | 51% | 47% | 51% | 54% |
| Other Income + | 1,911 | 1,819 | 1,082 | 1,373 | 1,083 |
| Interest | 290 | 333 | 955 | 1,111 | 880 |
| Depreciation | 2,917 | 3,264 | 3,466 | 3,634 | 3,789 |
| Profit Before Tax | 14,101 | 15,297 | 10,343 | 13,464 | 18,362 |
| Tax % | 32% | 31% | 25% | 24% | 25% |
| Net Profit + | 9,630 | 10,520 | 7,787 | 10,279 | 13,712 |
| EPS in Rs | 22.79 | 24.90 | 18.43 | 24.33 | 32.45 |
| Dividend Payout % | 79% | 303% | 71% | 119% | 31% |
The company’s future outlook is highly encouraging on account of capacity expansion and a marked improvement in operational efficiency. A higher hydro-smelter cell house current (212 kA) leading to the addition of 21 ktpa of refined zinc capacity, and the commissioning of a 160 ktpa roaster at the Debari plant have reinforced the production base. Operational efficiencies have improved through renewable energy (18%) and record domestic coal utilisation (53%). With over 25 years of mine life remaining and with the world’s largest zinc and lead reserves, the company benefits from strong integration, scale and long-term sustainability visibilities.
HZL has become considerably more interesting as an investment story because it is no longer simply a zinc company. Its zinc-plus-silver combination, very high margins, remarkably low-cost operations, strong cash generation and large dividend payments give it a distinctive position among Indian metal stocks.
The company started the new year (fiscal 2027) on a buoyant note with revenues in the first quarter (April-June 2026) amounting to Rs 13,747 crore, indicating a yoy growth of 77%, on which the company has earned a net profit of Rs 5,469 crore, suggesting a spurt of 145% over the corresponding quarter of fiscal 2026. Refined metal production during the quarter was 2,00,000 tonnes and silver production was 149 tonnes.
Interestingly, after the privatisation of HZL, silver has emerged as a major growth engine for the company, implying perhaps the most significant structural change in its story. Today, HZL is one of the world’s significant silver producers and India’s largest silver producer. Demand for silver has been on the rise as it is not only a precious metal but is also used in solar panels, industrial applications, electronics and electrical instruments, and data centres. In view of growing geopolitical tensions, silver prices have remained dull but once the war bugles stop blowing, silver prices are expected to resume an uptrend. The company is also planning to enhance its silver production capacity to 750 tonnes per annum in fiscal 2027.
The fundamentals of zinc – the company’s main product – have remained highly favourable. The metal is essential for galvanising steel, and therefore benefits from infrastructure and manufacturing activities. Today, India continuously spends on roads, railways, power transmission, renewable energy, automobiles and industrial machinery. Therefore, HZL’s future earnings will never be completely independent of commodity prices.
The company has been paying dividends regularly after privatisation. This has remained a major attraction for income-oriented shareholders. Besides, its strong cash generation allows it to distribute liberal amounts as dividends. For fiscal 2022, it paid a dividend of Rs 36.50 per share, for 2023 Rs 52 per share, for 2024 Rs 29 per share, and for 2026 it has paid an interim dividend of Rs 11.
One of the biggest attractions of HZL is its extremely high margins. It has been successful in controlling cost of production remarkably, increasing operational efficiency and pushing up profit margins. For example, for the first quarter of fiscal 2027, EBITDA was approximately Rs 8,074 crore, up 109% yoy. Historically, it has maintained very strong EBITDA margins because it benefits from captive mines, integrated mining and smelting, large reserves, a silver by-product, economies of scale and a relatively very low cost of production.
In the prevailing depressed market conditions resulting from growing geopolitical tensions, the share price of HZL is quoted lower at Rs 565. But once the war bugles fall silent, the share price is expected to rise. Some analysts have placed the target price at Rs 750 and a few feel that the scrip has the potential to even touch the four-figure mark.
– Savyasachi
September 30, 2026 - Combined Issue
Industry Review


VOL XVII - 13
September 16-30, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update