

Want to Subscribe?
Read Corporate India and add to your Business Intelligence
 Unlock Unlimited Access
Published: September 30, 2026
Updated: September 30, 2026
The RBI’s rejection of Tata Sons’ application seeking deregistration as a core investment company (CIC) implies that the company will continue to be in the list of NBFCs in the upper layer (NBFC-UL) that are required to list. Tata Sons was also in the first list of NBFCs-UL released by the RBI in October 2022. Under this framework, a company in this list has to get listed within three years.
Noel Tata, Chairman of Tata Trusts, which controls over 66% of shares in Tata Sons, is in favour of keeping the group holding company private, whereas the Shapoorji Pallonji (SP) group, which owns around an 18% stake in Tata Sons, is in favour of listing as it has a huge amount of borrowed funds and is keen to unlock the value of its investments, create liquidity and improve its credit profile.
As per media reports, various proposals are under consideration, including a buyback or offering the SP group shares in listed Tata group companies. However, recent developments indicate that it is becoming difficult for the Tatas to keep Tata Sons unlisted for long.
Under the circumstances, it would be interesting to look into some of the listed Tata group companies which have an equity stake in Tata Sons. If Tata Sons’ listing becomes a reality, these listed group companies would be at a great advantage because, collectively, seven such companies hold a 11.92% stake and all of them have been accounting their equity investments in Tata Sons at cost or at historical acquisition value. Once the entity gets listed, the accounting will mandatorily shift to a fair-value method, which will give them all the scope to strengthen their individual balance sheets and borrowing capacities.
Amongst these seven listed group companies, Tata Chemicals is at a great advantage. It holds 10,237 shares (2.53%) with a carrying investment value of Rs 57 crore. In contrast, an illustrative current fair-value translates into a realisation Rs 25,300 crore, whereas the current market capitalisation of the company is Rs 17,660 crore; i.e., just its investment in Tata Sons is higher by 43% to Tata Chemicals’ current market valuation. Though this is notional, it still matters a lot and reflects the company’s true intrinsic value.
It is important to mention that even if Tata Sons eventually lists in compliance with the RBI’s upper-layer NBFC rules, these listed group companies will be treated as long-term strategic promoters and will continue as they are rather than monetise their stakes. In other words, appreciation of the investments will remain in the books and not as liquid cash inflows.
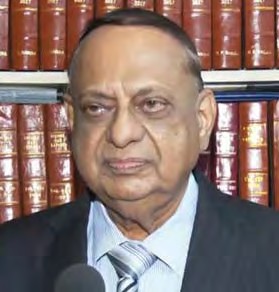
Homi P Ranina
Throwing more light on the internecine war in Bombay House, noted corporate law expert Homi P Ranina has stressed that shareholder majority remains absolute and minority objections do not hold legal firepower against the Tata Trusts and its governing Articles of Association.
Speaking to ANI vis-a-vis the controversy over the reappointment and extension of Tata Sons’ chairman, N Chandrasekaran, Ranina said the company’s Articles of Association mandate an affirmative vote from the majority of directors nominated by Tata Trusts. “Unless the affirmative vote is given by the directors who are nominees of Tata Trusts, the appointment cannot go through. The Supreme Court decided this point three years ago, holding that the affirmative vote requirement is entirely valid,” he noted.
On the issue of merging operating entities into Tata Sons to avoid the RBI’s mandatory listing fiat, Ranina noted that regulatory status depends strictly on asset composition. “If a company’s primary income ceases to arise from investments, it stops being classified as a Non-Banking Financial Company. Once the merger goes through and Tata Sons becomes an operating entity, it only needs to inform the RBI for de-registration. No prior permission is necessary,” he said.
On whether the Tata Trusts, which hold nearly 66 per cent equity in Tata Sons, can force structural restructuring onto a resistant board, Ranina affirmed that major corporate shifts rest entirely with shareholders rather than directors. “Directors have no power to decide this; it is a decision of the shareholders. At the AGM, the Trusts hold 66 per cent voting rights and can pass the resolution. Directors are not the ultimate decision-makers on mergers.” He added that Tata Trusts’ nominee directors must act in strict alignment with collective trust instructions rather than personal discretion.
In Tata Sons’ shareholding structure, Tata Trusts hold around 66 per cent, while the Shapoorji Pallonji Group owns 18.37 per cent. Tata Group companies together hold around 13 per cent in Tata Sons.
The issue around Tata Sons’ listing and leadership intensified in September 2026 after the RBI rejected Tata Sons’ application to remove its ‘Upper Layer’ NBFC status. Following this, the Tata Sons board voted 4-1 to reappoint N Chandrasekaran as Executive Chairman for a third five-year term and decided to initiate steps to comply with the listing requirement. Noel Tata, representing Tata Trusts, voted against the decision.
September 30, 2026 - Combined Issue
Industry Review


VOL XVII - 13
September 16-30, 2026
Want to Subscribe?
Read Corporate India and add to your Business Intelligence
Unlock Unlimited Access
Lighter Vein

1 Year *
Subscription
Rs 1800 /-
3 Year *
Subscription
Rs 5000 /-
5 Year *
Subscription
Rs 8000 /-
5
International
Subscription
$ 99.99
Read Corporate India and add to your Business Intelligence
Popular Stories
A modern-day enigma and a ramification of humanity's never-ending advancements, e-waste refers to the scum con- cealed by the outward glow of ever-advancing technology.
Archives
Office Address
Unit No. 405, 4th floor, Madhu Industrial Park, Avadh Narayan Tiwari Marg, Mogra Village Road, Andheri (East), Mumbai – 400069.
Call/Whatsapp
If you are interested in advertising with Corporate India, please don't hesitate to contact us. Our team is here to assist you with the process and answer any questions you may have. We look forward to the opportunity to work with you and help your business reach its full potential.
Fill out the form below to subscribe to our newsletter and never miss an update